Car Financing Options
When it comes to getting behind the wheel of your dream...
June 12, 2026
1. Executive Introduction
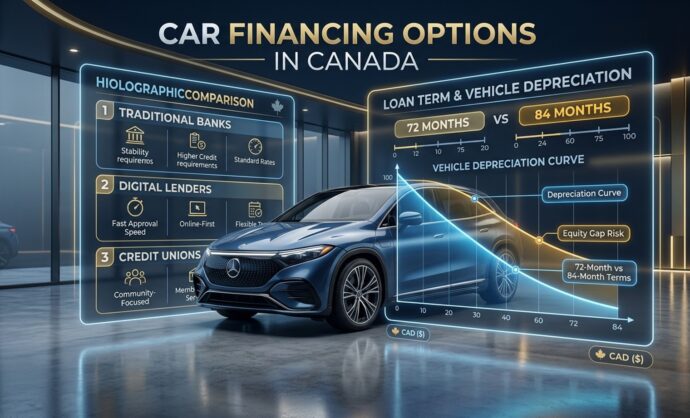
With average new vehicle transaction prices hovering near $45,000 CAD, an increasing proportion of Canadian buyers are opting for extended loan terms of 7 years (84 months) or 8 years (96 months) to achieve manageable monthly payments. Benchmark insights from Ratehub.ca – Best Car Loans in Canada Guide highlight the competitive landscape across Canada’s lending sectors while warning of the severe negative equity risks inherent in long-term amortization.
2. In-Depth Analysis & Market Evaluation
The Canadian Lending Landscape
Canada’s auto finance ecosystem features distinct provider channels: the Big 5 Banks (RBC, TD, Scotiabank, CIBC, BMO) offering prime rates near 7.20% with rigorous standards; digital platforms and fintechs (Clutch, Dealerhop, Loans Canada) offering streamlined approvals from 8.99% upward; and manufacturer captives providing specialized promotional incentives.
The Negative Equity Trap (Being Underwater)
Vehicles are depreciating assets that typically lose 20% to 30% of their value in the first year, followed by steady annual declines. On an 84- or 96-month financing term, initial monthly payments primarily cover interest charges rather than principal amortization. As a result, the outstanding balance on the loan exceeds the vehicle’s fair market value for the first 4 to 5 years.
Compounding Risks in Premature Trade-Ins
If the vehicle is totaled in an accident or the owner needs to trade it in prematurely, the borrower must cover the difference out-of-pocket or roll the deficit into a new loan, creating an escalating cycle of compounding debt that severely restricts financial freedom.
| Financing Term | Monthly Payment (45k Loan) | Total Interest (7.2% APR) | Equity Positive Point | Risk Assessment |
| 48 Months (4 Years) | $1,081 / mo | $6,908 CAD | Month 14 | Low Risk (Rapid Equity) |
| 60 Months (5 Years) | $895 / mo | $8,720 CAD | Month 24 | Moderate Risk (Balanced) |
| 72 Months (6 Years) | $771 / mo | $10,540 CAD | Month 38 | Elevated Risk (Watch Equity) |
| 84 Months (7 Years) | $684 / mo | $12,450 CAD | Month 54+ | Severe Negative Equity Trap |
3. Conclusion & LoanWhiz Advisory
To maintain financial flexibility and avoid negative equity traps, adopt prudent borrowing boundaries aligned with sound wealth-building principles.
| LoanWhiz Long-Term Vehicle Ownership Rules • The 20/4/10 Guideline: Aim for at least a 20% down payment, finance for no longer than 48 to 60 months, and ensure total transportation costs do not exceed 10% to 15% of gross monthly income. • Explore 2–4 Year-Old Certified Pre-Owned Vehicles: By purchasing a lightly used vehicle that has already absorbed the steep initial depreciation drop, you significantly lower loan exposure while retaining reliability. • GAP Insurance Considerations: If you must finance with a minimal down payment or on an extended term, ensure GAP (Guaranteed Asset Protection) coverage is in place to safeguard against total vehicle loss liabilities. |
Imagine walking into a car dealership, eyes fixed on th...