The consumer credit market in Canada is witnessing a striking divergence in vehicle financing: while aggregate debt balances continue to surge to unprecedented levels, origination volumes of new loans are experiencing a noticeable contraction. Data from Equifax Canada Market Pulse and recent market analysis from ON-U – What Used Car Dealers Need to Know for Fall 2026 demonstrate that Canadian households are facing severe affordability pressures as vehicle acquisition and borrowing costs remain elevated.
In-Depth Analysis & Market Evaluation
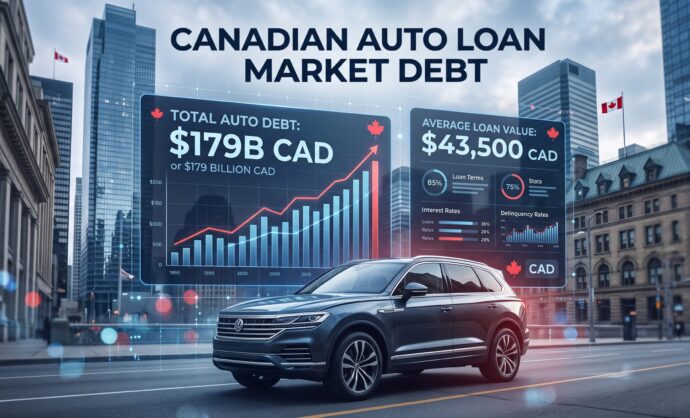
- Balance Growth Driven by Higher Average Loan Sizes:Total outstanding auto loan debt across Canada has reached $179.1 billion CAD, representing a 4.9% increase year-over-year. Crucially, this expansion is not fueled by an increase in vehicle sales, but by a substantial jump in the average size of newly originated auto loans—climbing from $34,713 CAD to $36,979 CAD. Price escalation in raw components, shipping costs, and a market shift toward higher-tier SUVs and electrified powertrains have driven up financing amounts.
- Consumer Hesitation and Delayed Replacement Cycles:The number of newly opened auto loan accounts contracted by 9.2% year-over-year. Across major economic hubs like Ontario and British Columbia, employment uncertainty and broader cost-of-living increases have led consumers to retain their current vehicles longer rather than taking on new debt commitments.
- Credit Risk Divergence Between Banks and Alternative Lenders:Severe 90+ day delinquency rates among non-bank auto lenders continue to experience upward pressure, reflecting the strain on non-prime and subprime borrowers who have fewer cash-flow buffers to absorb sustained four-figure monthly living and transportation expenses.
Conclusion & LoanWhiz Advisory
Growing individual debt burdens underscore the necessity for disciplined financial planning prior to purchasing a vehicle.
- The 15%–20% Net Income Rule: Keep total monthly automotive outlays (including principal, interest, auto insurance, and fuel) strictly within 15% to 20% of your take-home pay.
- Capitalize with Equity Upfront: Provide a minimum cash down payment of 10% to 20% to lower the initial principal balance and minimize cumulative interest charges over the life of the loan.