The automotive financing landscape across the United States and Canada is undergoing a significant transformation. Between record-high vehicle prices, extended amortization periods, and shifting credit underwriting policies unveiled at major industry forums like the Auto Finance Summit 2026, both consumers and lenders are recalibrating how vehicles are bought, financed, and serviced.
Drawing upon recent market intelligence and the advisory principles of LoanWhiz, here is an executive briefing on the state of auto financing in North America and what it means for consumers and industry stakeholders.
1. The Affordability Squeeze: Record Loan Amounts and Payments
Vehicle affordability remains the defining issue of the market in 2026:
2. Stretching Loan Terms: The 77-to-84 Month Reality
To keep monthly payments manageable within household budgets, borrowers and lenders are extending terms:
- Average Term Surpasses 6 Years: At the Auto Finance Summit 2026 in Las Vegas, major dealership groups reported that average loan terms have climbed to 77 months, as highlighted by Auto Finance News – Morgan Auto Average Loan Term Reaches 77 Months.
- The Negative Equity Risk: Over 25% of new car loans now exceed 84 months. While stretching terms lowers the monthly commitment, it exposes buyers to prolonged negative equity (being “underwater” on their car loan), where depreciation outpaces principal amortization.
3. Lenders Tighten Credit and Pivot to Prime Portfolios
In response to sustained default pressures and economic headwinds, major institutional lenders are adjusting their risk tolerance:
4. The Canadian Picture: Slower Unit Sales, Rising Balances
In Canada, the consumer credit dynamic reflects similar structural shifts:
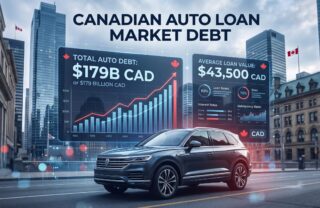
- Debt Expansion Despite Volume Slowdown: As highlighted in ON-U – Canadian Auto Loan Market Analysis & Delinquency Trends and Equifax Canada Market Pulse, total Canadian auto loan balances reached $179.1 billion CAD (up 4.9% YoY), while the average new loan value climbed to $36,979 CAD.
- Consumer Hesitation: Canadian buyers are increasingly holding off on major upgrades or turning to pre-owned vehicles, waiting for clearer monetary policy signals from the Bank of Canada.
5. Technology and Refinancing Solutions
Lenders and fintechs are deploying digital tools to maintain liquidity and aid borrowers:
The LoanWhiz Advisory: 4 Practical Rules for Vehicle Buyers
- Get Pre-Approved with a Soft Pull First:Before visiting a showroom, secure a pre-qualification that does not impact your credit score. Knowing your exact approved rate and budget sets clear guardrails and protects against dealership rate markups.
- Prioritize 10%–20% Down Payments:Placing adequate equity down cushions against the initial 20%–30% depreciation hit and prevents carrying negative equity into your next trade-in.
- Beware the 84-Month Trap:Avoid extending loan terms past 60–72 months simply to fit an expensive car into a monthly payment target. If a vehicle requires an 84-month term to be affordable, consider a reliable 2–4 year-old pre-owned vehicle instead.
- Account for the Total Cost of Borrowing:Calculate comprehensive monthly vehicle expenses—including insurance premiums, provincial/state sales taxes, fuel, and warranty protection—keeping automotive outlays under 15%–20% of net monthly income.